Marco Valle, Azimut/Benetti: Large Yachts Growing, We Won’t Make Unreasonable Offers for TISG
Marco Valle, Azimut|Benetti: Large Yachts Growing, We Won’t Make Unreasonable Offers for TISG
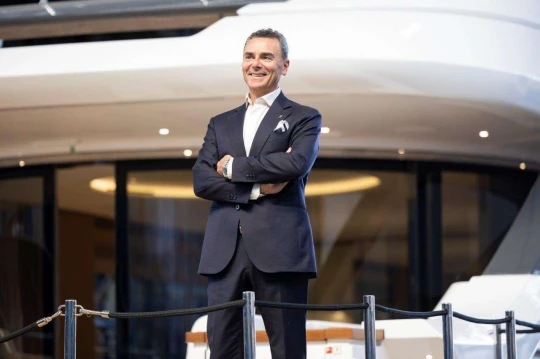
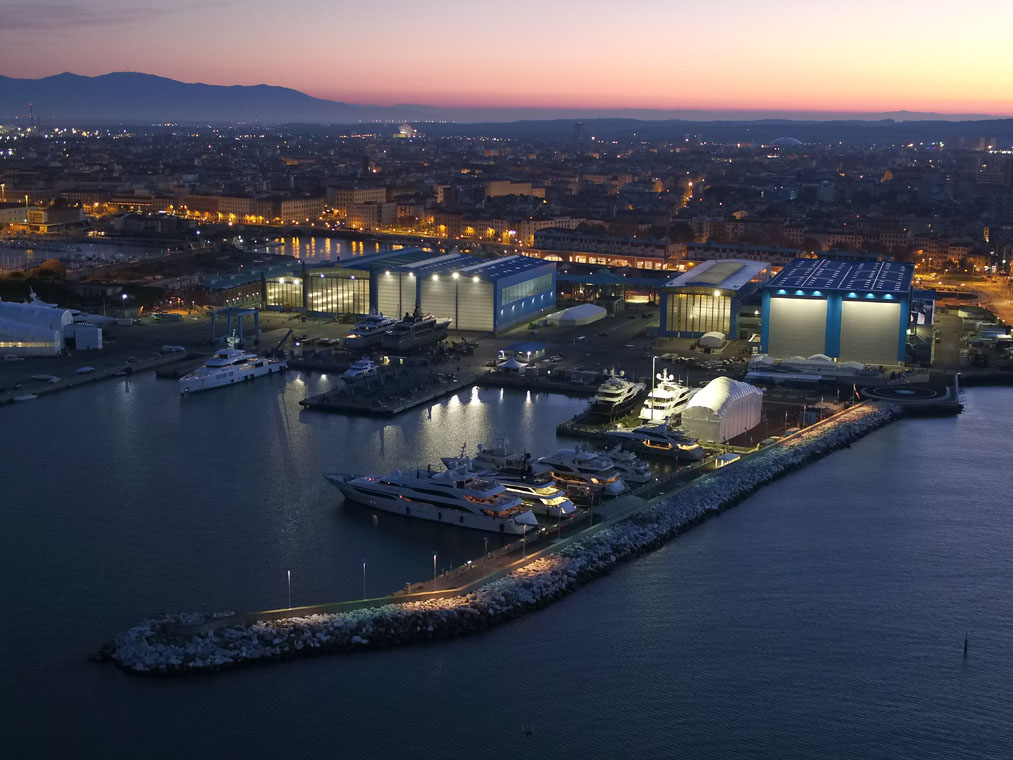
The most interesting aspect of the current phase for Azimut/Benetti is not simply the number of yachts sold. It is time. For some custom steel yachts, the first available build slots now extend as far as 2030, and when an owner has to be told that they will need to wait four or five years, a strong order book can paradoxically become a constraint. This is the starting point for Marco Valle, CEO of Azimut/Benetti Group, as he discusses production capacity with PressMare at the Genoa International Boat Show – a subject that inevitably intersects with the The Italian Sea Group dossier.
PressMare – Benetti has a substantial order book. How is the large-yacht market performing?
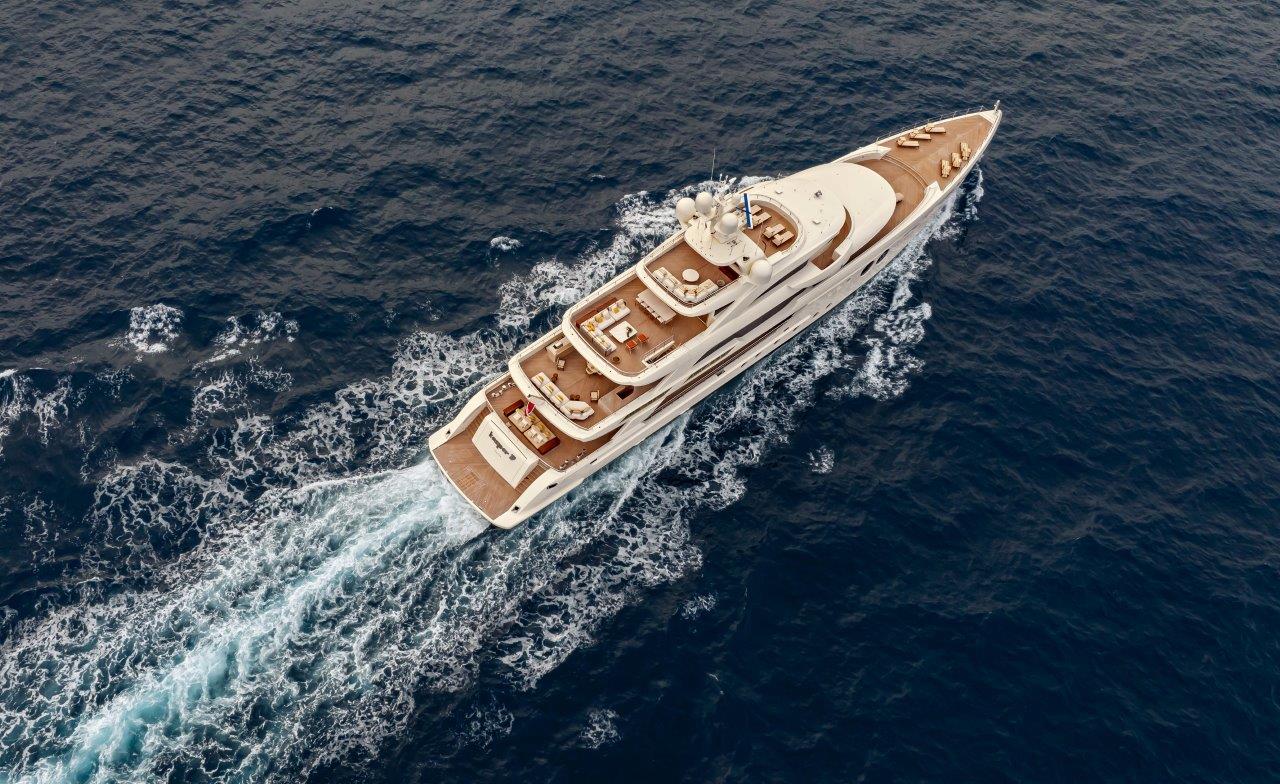
Marco Valle – We have very long-term visibility, and that is the result of several factors: successful products, consistency over time, continuously improving quality and, above all, our ability to meet delivery schedules in recent years. Anyone visiting Livorno finds a clean, well-organised shipyard that works efficiently: even our Northern European competitors, when they visit us, take their hats off to what they see. The large-yacht market remains very positive. Turkish shipyards are going through a more challenging phase, mainly because of rising costs, while Northern European builders have focused on yachts above 80 metres, often over 100 metres, with order books extending far into the future. This creates an important opportunity for Italian shipyards, which today represent a genuine alternative for owners looking for yachts between 50 and 80 metres. In this scenario, the difficulties facing The Italian Sea Group effectively remove one competitor from the market. Among the Italian shipyards active in this size range are Rossinavi, Codecasa and Palumbo, which produce relatively limited numbers, followed by ourselves, CRN and Sanlorenzo. There are not many operators capable of meeting this demand.
PM – Cannes, Monaco and Genoa marked the beginning of the European yachting season. What is your assessment from a commercial standpoint?
MV – Cannes went very well, I would say better than last year. Azimut signed several contracts, while Benetti concluded a number of LOIs – letters of intent – which we are currently working on. Activity was particularly strong in the mid-to-upper segment, although there were also sales between 50 and 60 feet. Not all segments are performing in the same way and some are more challenging, but above 26 metres demand remains strong. We concluded some important sales and the Magellano 27M received a positive response; at Cannes we sold four Seadeck 9s and, if everything goes according to plan, we could close the fifth sale in Genoa. Monaco also produced positive results with the Grande 44M and, more generally, with yachts above 35 metres. For Benetti, the Monaco Yacht Show was particularly intense, with virtually back-to-back appointments, and we are seeing growing demand for custom and full-custom projects. Several negotiations are currently under way for yachts between 50 and 90 metres.
PM – Could this therefore lead to further growth in yacht size as well?
MV – We need to maintain an industrial balance. Personally, I believe that at this stage 90 metres is a threshold beyond which we need to proceed with great caution. We have a diversified production structure between Livorno and Viareggio, building in both fibreglass and steel, and we want to maintain the right balance. We must not repeat the mistakes of the past by necessarily pursuing ever-larger dimensions.
PM – The issue of production capacity brings us to The Italian Sea Group. For some time, there had been talk within the industry of yachts being offered at prices that other builders considered unsustainable because they were below their own industrial costs. How much did this commercial policy affect competition?
MV – Every company is free to establish its commercial policy as it sees fit. It is not for me to determine at what prices Giovanni Costantino could or should have sold his yachts.
PM – When we put the same question to Costantino, he told us those prices were the result of optimising production processes and industrialising yacht construction…
MV – That means he was very good at selling. We too lost a few contracts to The Italian Sea Group, just as can happen with any other competitor: that is part of the market. I repeat, I do not want to comment on another company’s commercial policies. When TISG’s difficulties emerged, my main concern was something else: the potential impact on the credibility of the Italian yacht-building industry among international clients.
PM – Have you seen any tangible repercussions?
MV – At the beginning, yes, to some extent. Imagine a broker negotiating with a client who, for whatever reason, would prefer to steer that client towards a Dutch or German shipyard: they could use what is happening to an Italian builder as an argument for saying it would be better not to buy in Italy. We do not know what a broker and a client say to each other, but situations like this do not help the image of the Italian industry. Today, however, looking at our commercial results and the contracts we continue to sign, I do not think the problem is still there. I know that Costantino is doing everything possible to save his company: that is his job and there is nothing wrong with trying. There are several interested parties, and we will have to see how the process develops.
PM – Giovanna Vitelli has already publicly confirmed Azimut/Benetti’s interest in The Italian Sea Group and its participation in the sale process. What would be the scope of a potential acquisition for you?
MV – We are carrying out our assessments, but we are certainly interested in the entire package. The deadline for submitting final offers is approaching, on 19 October, and we need to understand whether the conditions exist for an operation of this kind.
As a Group, we need production space – for Azimut, for Benetti and for Lusben. It is no secret that in recent years we have looked for new opportunities in the Navicelli area and assessed alternatives to Viareggio. The need exists, but we are not prepared to make unreasonable offers: that is not the way we work. We assess industrial opportunities, economic conditions and the overall sustainability of the investment.
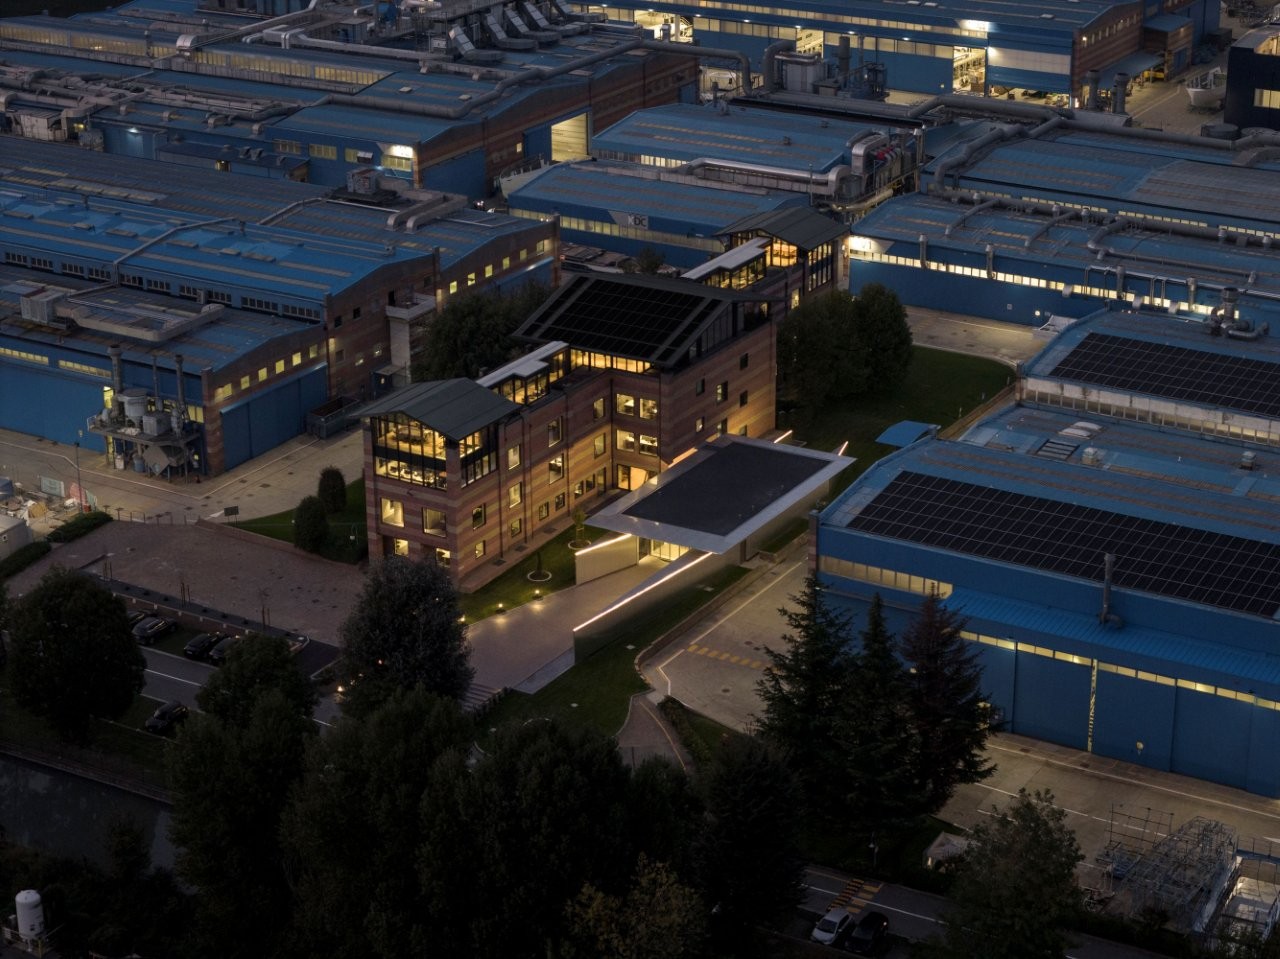
PM – Particularly because TISG’s financial situation appears extremely complex: there has been talk of around €400 million in debt.
MV – That is what the newspapers are reporting. What I can say is that the situation is objectively very complex.
PM – If Azimut/Benetti had additional production facilities available, by how much could you increase large-yacht production?
MV – Livorno is a larger facility, but TISG’s facilities are also significant. Our five-year industrial plan includes new products in both fibreglass and steel, and suitable production berths and facilities are required to build them. We are assessing TISG’s facilities just as we have assessed other sheds and other opportunities: the objective is to have the industrial capacity required to support our future programmes.
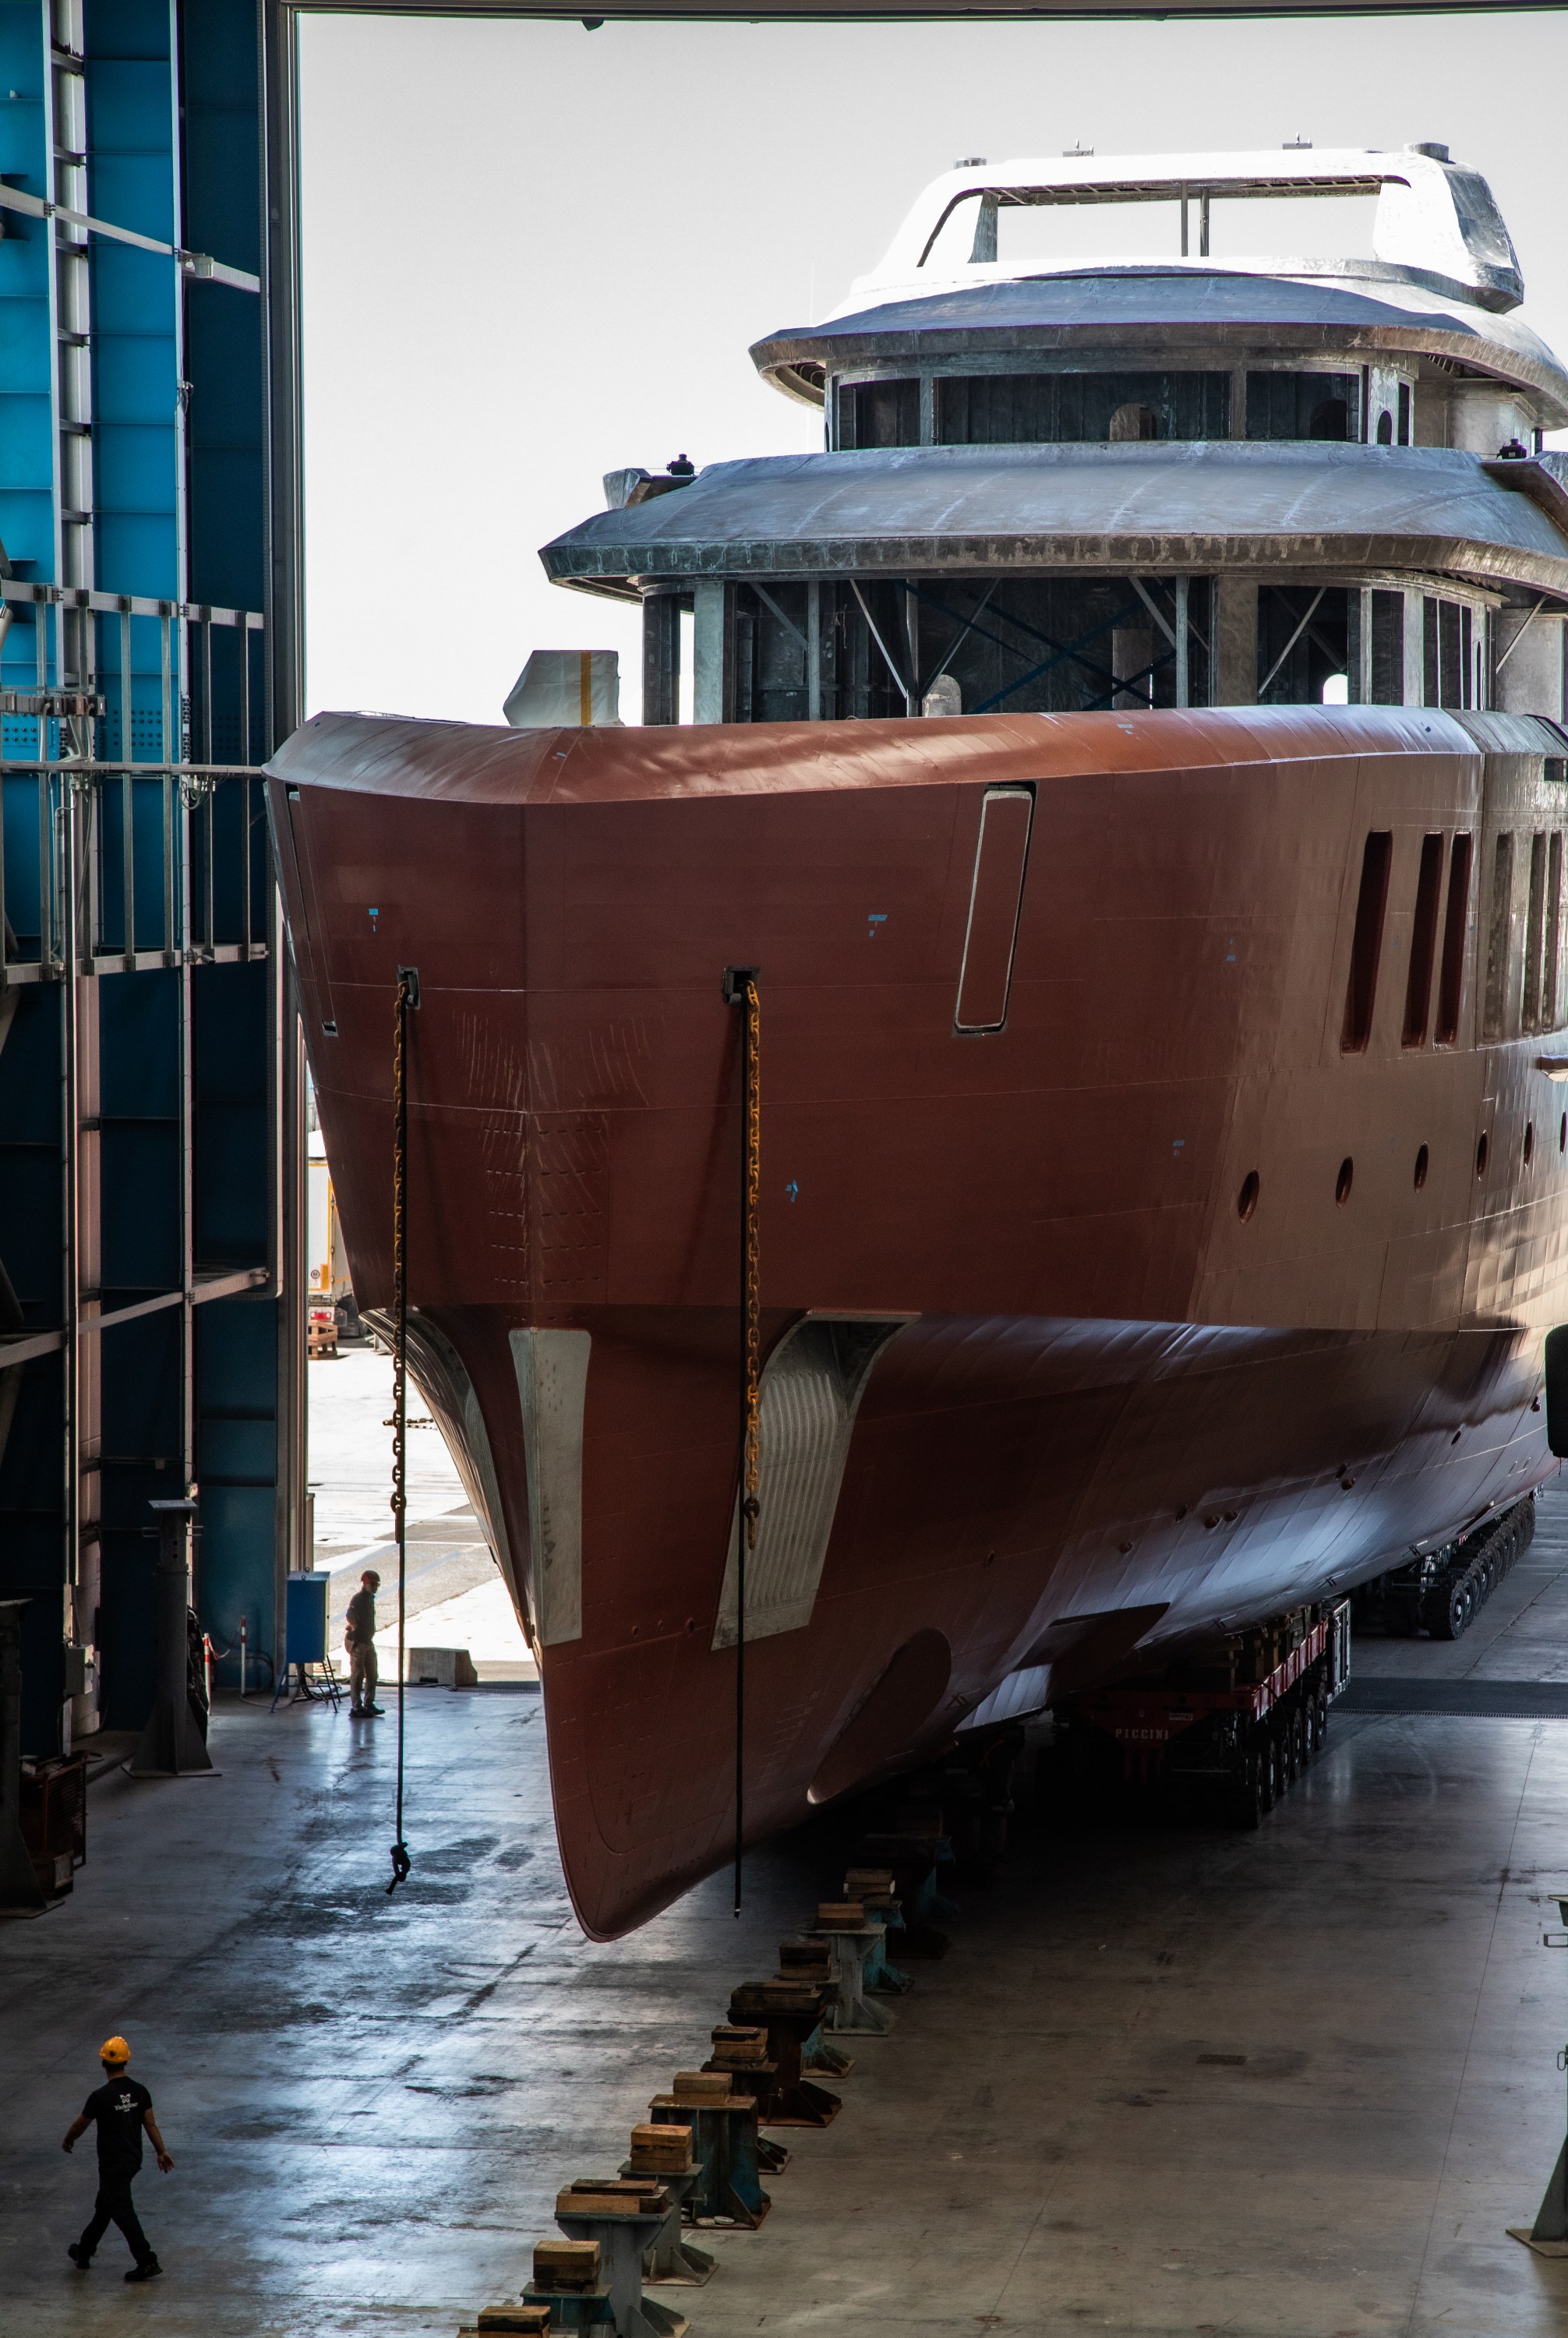
There is another aspect as well. Demand for custom steel yachts is high and, under the best circumstances, we can currently offer deliveries around 2030. Telling a client that the next available slot is in 2030 or 2031 means running the risk of losing them. This is another reason why we need to understand how to increase our production capacity.
PM – Do you have the possibility of building some yachts on speculation, without an owner already identified, in order to reduce delivery times?
MV – No, because everything is sold. And this brings me back to a concept I often repeat: cash does not lie. Our Chairman has stated several times that we have a positive cash position of more than half a billion euros, and that figure needs to be considered alongside the order book. If you have a substantial order book but a financial position that is not consistent with it, you need to ask yourself how solid those orders really are. A client signing a contract must pay a deposit and comply with the scheduled payments during construction: from a financial standpoint, a contract based on a promise or a handshake is worth nothing. I remember the 2008 crisis very well. At the time, someone explained a concept to me that I have never forgotten: companies do not fail because they lack orders, they fail because they lack cash. If clients do not pay, a full order book will not save anyone.
PM – From this standpoint, Azimut/Benetti therefore has the financial capacity to undertake such a significant potential acquisition using its own resources…
MV – We have zero debt, zero leasing and a lot of cash.
PM – Do owners ask you for bank guarantees on their payments?
MV – When they are requested, we provide them. Today banks would like to lend us money, but we do not need it. It is an optimal situation, the result of a corporate culture that has existed for a very long time. We do not accumulate financial resources simply for the sake of doing so: they are there to invest, develop new products, avoid cutting corners on quality and ensure the company remains financially sound even when the market goes through a downturn. I believe Azimut/Benetti is one of the financially strongest companies in the yachting industry, if not the strongest – certainly among the leading ones.
PM – Let’s return to the Genoa Boat Show. We know Azimut/Benetti was among the supporters of moving the show to October, after Monaco. Based on this edition, has the decision worked?
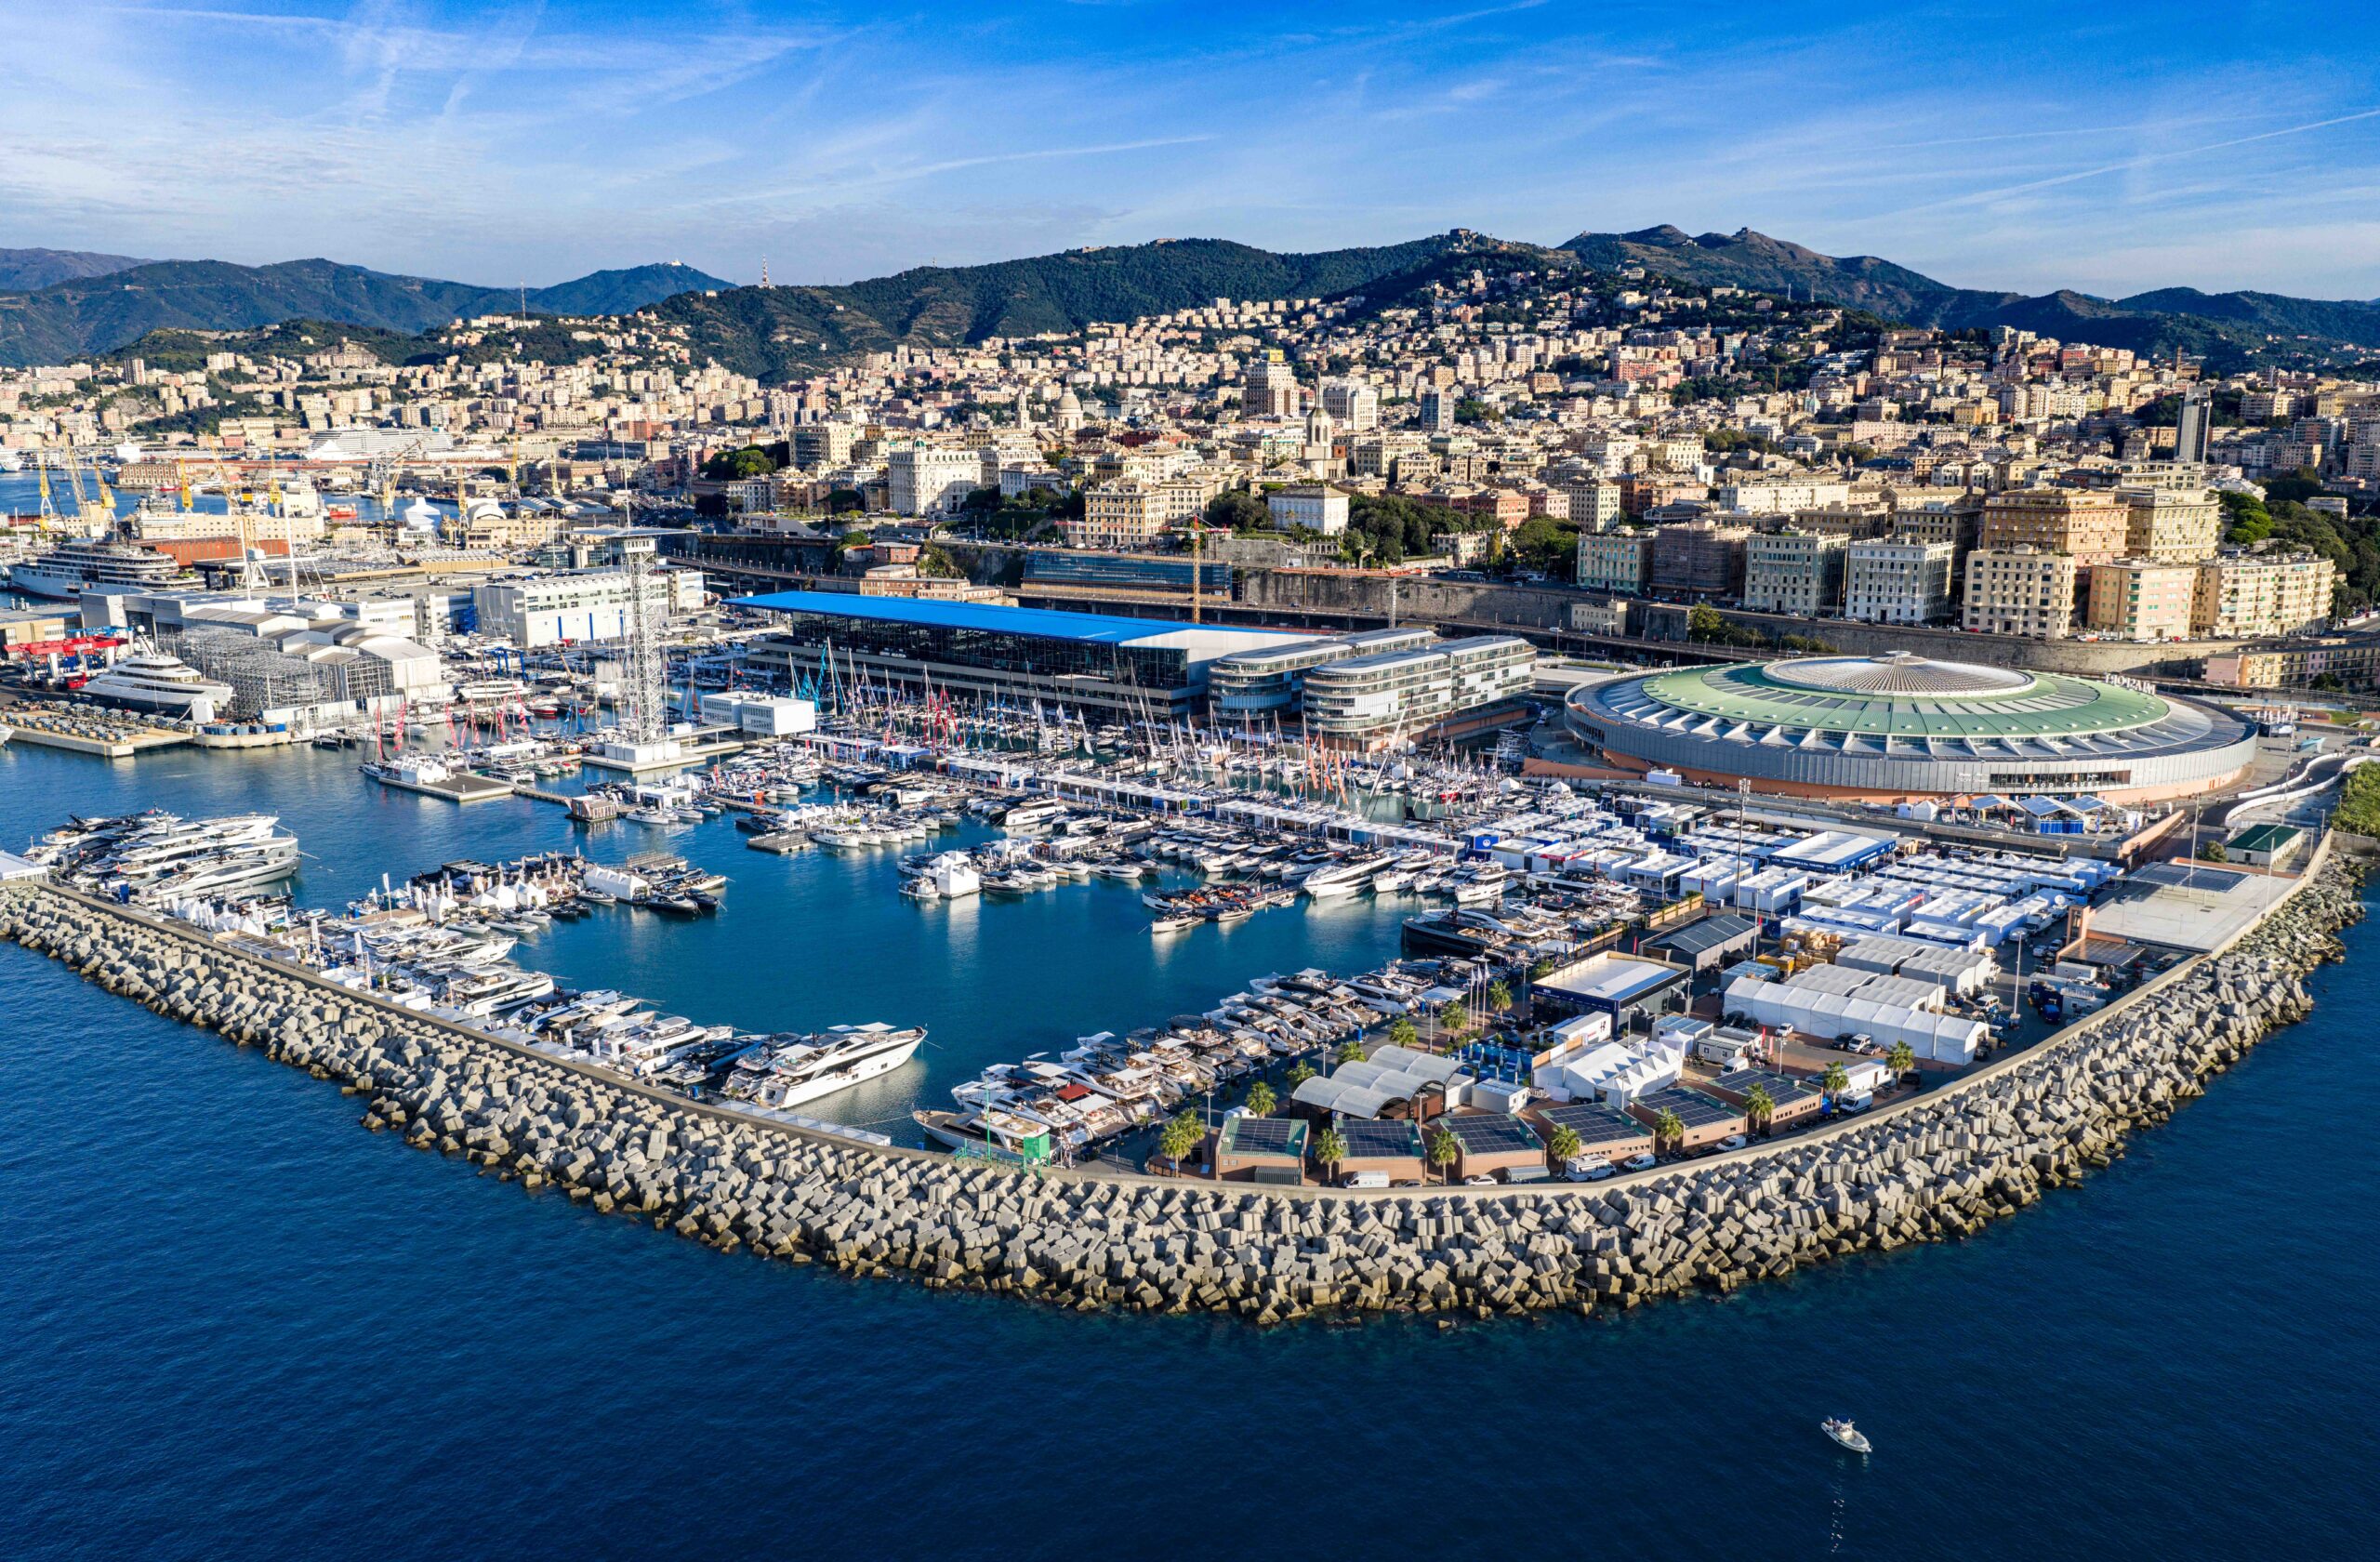
MV – Absolutely, and we supported it from the outset. I am a member of Confindustria Nautica and, as a member of the Council, I strongly backed this decision. As a Group, we use a registration system at all boat shows: every appointment and every visit is recorded, distinguishing existing clients from potential new clients, while excluding the press and casual visitors from the count. During the first three days in Genoa, we recorded an increase of around 30%, a result that was subsequently confirmed by the end of the boat show. We also concluded two sales in the first few days, with clients we had already met in Cannes and invited back to Genoa, followed by a third sale.
PM – Was this one of the arguments in favour of changing the dates?
MV – Exactly. When Cannes takes place at the beginning of September and Genoa follows immediately afterwards, even a client with substantial financial means is unlikely to be interested in returning just a few days later to see the same yacht. They have not had time to reflect and reach a decision and, sometimes, they have not even received a written offer because the dealer or shipyard simply has not had enough time to prepare it. With a month between the two shows, however, you can work on the negotiation: prepare the offer, allow the client to assess it, discuss it and absorb all the information. At that point, you can invite them to Genoa to continue or conclude the negotiation. Our records also show a greater presence of international clients. The show therefore becomes a second commercial opportunity rather than simply a repeat of the first event.
PM – Could Genoa also become an opportunity to present new Azimut models?
MV – This year, Azimut brought four new yachts to Genoa, some of them very important for their respective ranges: the Seadeck 9 is the flagship of the Seadeck line and of production at Avigliana, the Magellano 27M marks a further evolution of the Magellano family, and then there is the Grande 44M. It is the largest yacht ever built by Azimut. Product presentations, however, must also follow commercial requirements: a new model needs to be shown at the beginning of the season, without necessarily waiting until October.
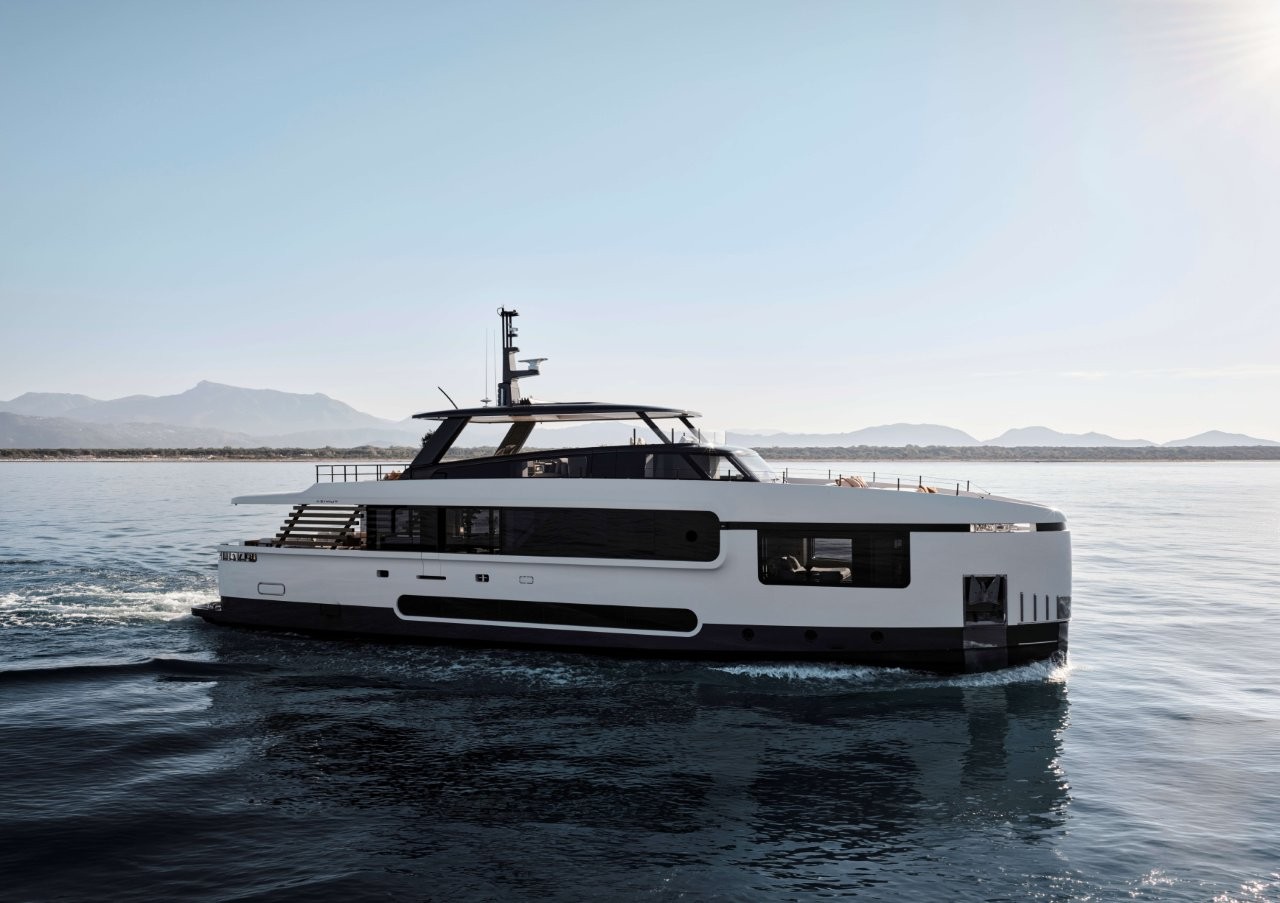
PM – This year you also invested in the presence of large yachts in Genoa, bringing them together in a dedicated area. How do you assess this first experience?
MV – Together with Piero Formenti, we wanted to invest in large yachts at the show and, also thanks to Overmarine, we involved other shipyards, asking each of them to bring one yacht. There were five of us, and that is already a positive sign. The area, however, needs to be developed further. A large-yacht builder does not need hundreds of visitors every day: over five days, just one genuinely interested client can be enough to justify participating.
We need to make the area more exclusive and prestigious, with an access system and a layout that immediately convey the feeling of entering a different environment. I have a few ideas to bring to the Council: as shipyards, we know what our clients are looking for because we continuously organise events, presentations and dedicated visits, and we can put this experience at the organisation’s disposal. The facilities improved this year, but products in this segment require a further step up in quality. It is not enough simply to display a large yacht; the surrounding environment also needs to be consistent with the product.
PM – Let’s move to international markets. Given the geopolitical situation, how is the Middle East performing, considering that it appeared to be entering a period of strong growth?
MV – The Middle East remains a very important market. The issue mainly concerns boats intended to remain permanently in the region. For some small and medium-sized boats sold to clients intending to use them in the Gulf, we have encountered difficulties even in transferring them to their final destination. One boat remained stuck for months because it was unable to transit the canal.
The situation is different for larger yachts, such as Azimut Grande models or Benettis: many Middle Eastern owners buy them to use in the Mediterranean, so we have not encountered the same problem. The 50-to-70-foot segment, and more generally yachts up to around 80 feet, has instead experienced a slowdown. No one could have predicted how the conflict would evolve. In our forecasts, we had already factored in a US market that would be somewhat less buoyant than other regions, and this effect was also offset by a major contract in the Maldives. Overall, thanks to the geographical distribution of our sales, we are fairly comfortable with our expected results.
PM – And the United States?
MV – I am convinced that the US market could recover strongly this year. The main risk remains inflation, but dealer inventories are much lower than they were a few years ago, and that is a positive factor. I also believe our products are particularly well suited to American clients.
PM – In the United States, you have a long-standing relationship with MarineMax. Could the ongoing change of ownership alter anything?
MV – We will find out. I do not believe there will be any significant changes in the short term. MarineMax is a listed company with a very substantial organisation and an extensive presence throughout the United States, and completion of the transaction is expected by the end of the year. In the meantime, the Fort Lauderdale International Boat Show is ahead of us, where we expect intense commercial activity. The Seadeck is performing particularly well in the United States today, especially in Florida: we have probably sold more units there than in Europe.
PM – It does indeed seem particularly well suited to that market.
MV – Yes, because it is perceived as a day boat, or something slightly larger, and it fits very well with the habits of American owners, many of whom operate their own boats. In Europe, by contrast, we are increasingly seeing owners who prefer to have a captain even on relatively small yachts – a trend that, in my view, could create some problems in the future.
The Seadeck lends itself very well to owner-operation: it is a highly liveable boat, with spaces that open towards the sea and a very direct relationship with the outside environment, while still providing everything needed for boating in places such as Florida, where air conditioning is essential. In some respects, it represents the evolution of concepts already present in the US market: twenty years ago there were express cruisers, then centre consoles became increasingly popular, and the Seadeck interprets some of those requirements in a different way.
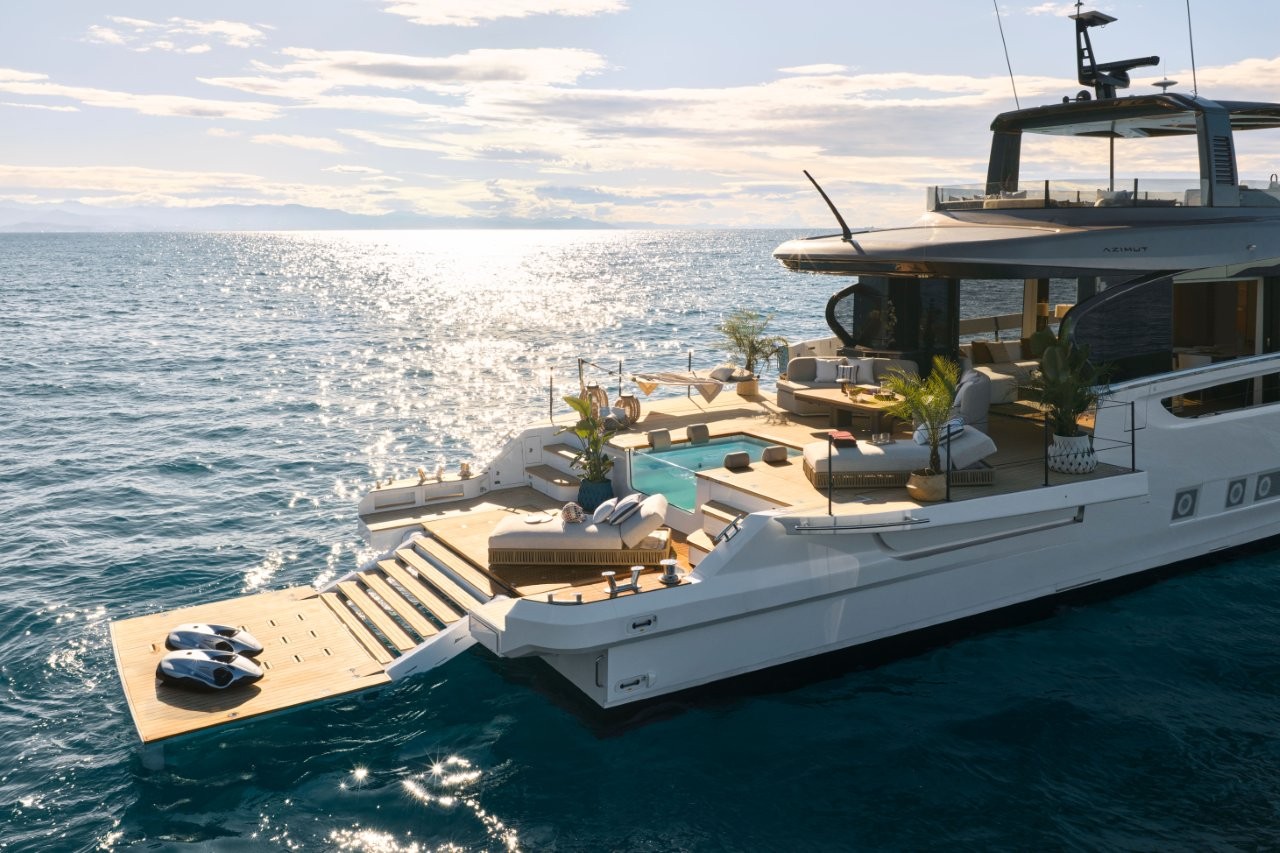
PM – In Monaco, you also presented a very distinctive Benetti project built around the concept of the “wow effect”. What is the philosophy behind it?
MV – The project comes from the combination of several elements. The original idea was to create a yacht designed around people’s wellbeing, but by wellbeing we do not simply mean having a gym or a spa on board. We have also worked on the concept of longevity, without simply following a trend. Wellbeing depends on many factors – sleep quality, light, sound and the environment in which we live – and we have tried to integrate these elements directly into the yacht’s design.
One of the most interesting solutions is the large dome covering an area that would normally be open, transforming it into a space that can be used in different ways, both during the day and at night: a kind of winter garden. A structure of this kind, however, creates an air-conditioning challenge, so we considered using the dome surfaces to generate energy, with photovoltaic panels integrated into the glass and featuring different characteristics depending on the level of transparency required. The objective is to offset at least part of the energy required for climate control with the energy generated by the roof itself. I think it is a fantastic idea.
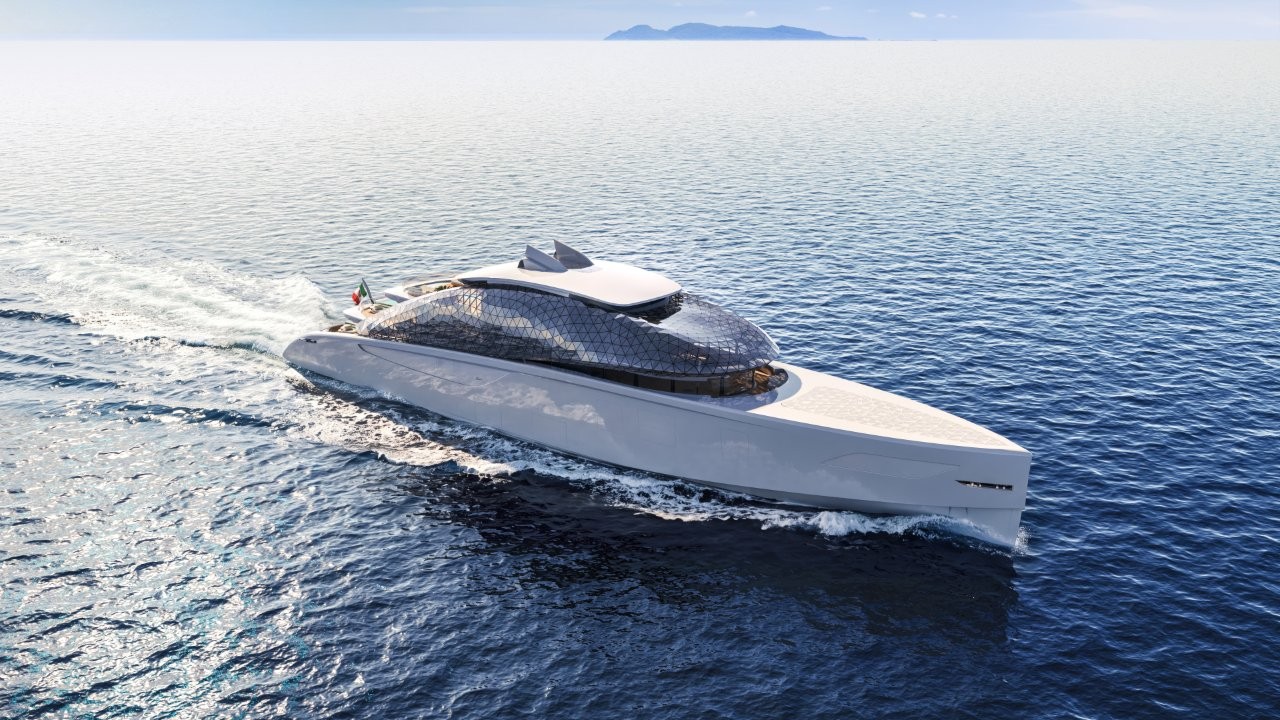
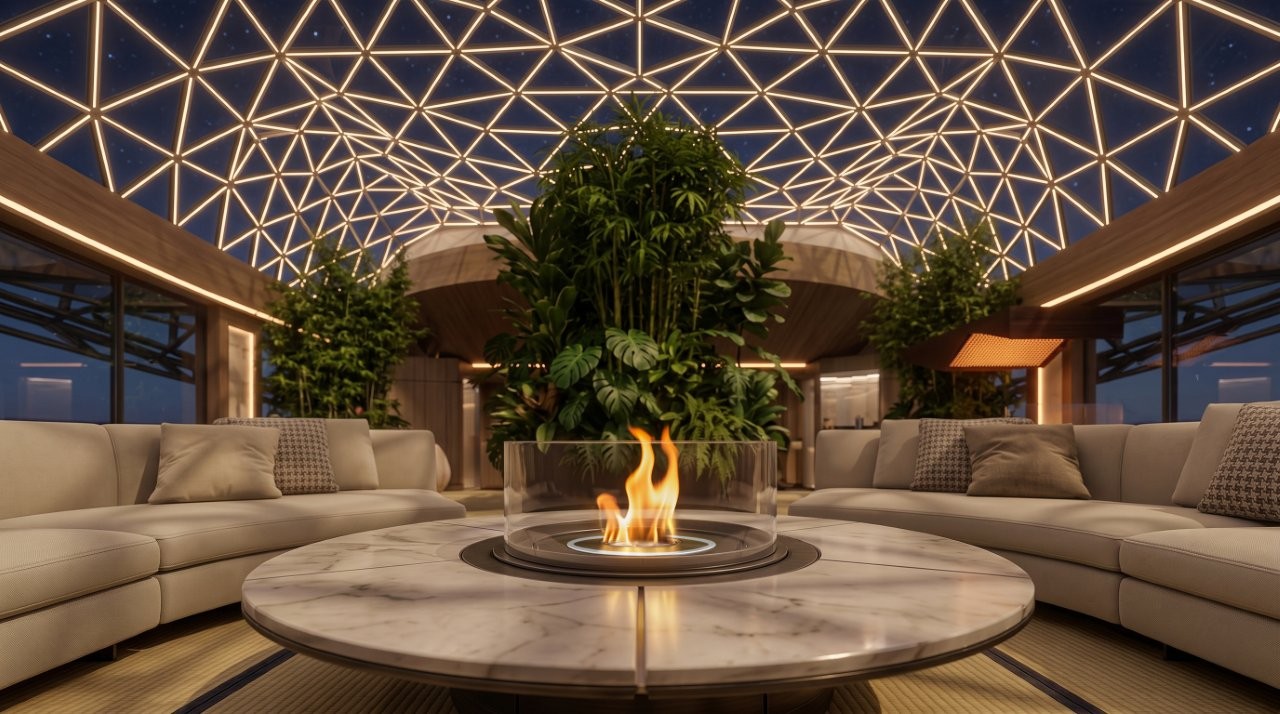
PM – Many concepts presented at boat shows remain styling exercises. Can this one actually be built? And how has the market responded?
MV – The response exceeded our expectations and the project is feasible: we do not allow technically unfeasible solutions to be presented. We have been working on it for at least a year and a half, perhaps longer, and we would have liked to present it at last year’s Monaco Yacht Show, but we were not ready. We preferred to wait in order to verify the feasibility of the dome, the structures and the other solutions.
I personally followed the project with Giovanna Vitelli and we visited Luca Dini several times to discuss it. A specialist supplier came to assess the project and confirmed that the structure can be built. Benetti has credibility to protect: if we present a project, the client must know that they can buy it and that we are capable of building it. It is not a styling exercise; it is a yacht that can actually be built. Of course, it requires a client willing to choose something innovative and experiment with a different way of experiencing a yacht.
PM – Benetti is going through a particularly positive period. I would, however, like to return to Azimut and the Avigliana facility: when I visited it last winter, I had the impression that it was not operating at full capacity.
MV – We need to distinguish between the number of boats produced and the amount of work required to build them. The production mix has changed: we are building fewer boats in numerical terms, but they are larger and have greater internal volume, therefore more gross tonnage, so the amount of work required has not decreased.
The number of people employed is essentially the same as last year: we have no issues involving workforce reductions and, in fact, we will probably need to hire some additional people. Our production schedule ensures continuity for the next three years and is the result of an industrial strategy launched several years ago. We expanded and rationalised the facilities, built new sheds and invested to enable Avigliana to build boats that would once have been unthinkable for that facility. Today we can build fibreglass hulls of around 26 metres there, such as the Seadeck 9 hull, and we have constructed a new paint hangar sized to accommodate them. Next year we will introduce another important boat.
PM – And Brazil, where you have a shipyard in Itajaí?
MV – Very well. This year we will produce around 38–40 boats and we continue to invest in the Brazilian facility: we have planned an expansion worth approximately €11 million. We have already started laminating the hull of a new 30-metre model, which we expect to present in Brazil towards the end of next summer. At the São Paulo Boat Show, held at the same time as Genoa, we already presented a mock-up.
It is an Italian project that will also be built in Brazil, following the same strategy adopted for the 27-metre model, which achieved excellent commercial results in the Brazilian market. Brazil remains an excellent market for us: Azimut is perceived as the premium brand par excellence, and that represents a very important competitive advantage.
PM – And Asia? Projects aimed at developing recreational boating in the Far East, including new marinas and infrastructure, are multiplying.
MV – Asia is a fairly stable market. New marinas and infrastructure are being developed, but we need to avoid generalisations. It is an enormous region comprising profoundly different markets: China is not Japan, and Singapore has different characteristics again, with cultures, habits and purchasing patterns that cannot be treated as a single market.
It is true that Asia has a very significant concentration of wealth, and we are also seeing used yachts moving from Hong Kong towards Europe, which is another factor to consider. We have built a very extensive distribution network, with dealers operating in the different markets, each with specific commercial objectives. An individual dealer may sell only one or two boats, but with twelve dealers the overall result becomes significant. As Totò used to say, it is the sum that makes the total.
Fabio Petrone
©PressMare - All rights reserved